The Over-Hedging Fallacy: How Excessive Liquidity Buffers Erode Mid-Market ROIC
Why mid-market Australian boards mistakenly treat idle balance sheet cash as risk mitigation rather than an unpriced drag on capital efficiency and enterprise value. eroding overall enterprise value
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed October 2026. Next review scheduled for December 2026.
TL;DR
Why mid-market Australian boards mistakenly treat idle balance sheet cash as risk mitigation rather than an unpriced drag on capital efficiency and enterprise value. [eroding overall enterprise value](/insights/business-valuation-methods-australia)
Key Takeaways
- The Negative Spread Reality: Retaining idle liquidity when the corporate cost of capital exceeds short-term deposit yields actively destroys shareholder equity on an inflation-adjusted, post-tax basis.
- Statutory Solvency versus Excess Buffers: Compliance with ASIC regulatory guidelines and s 588G requires demonstrable liquidity through structured access to capital, not exclusively static cash hoarding on the balance sheet.
- M&A and Valuation Multiple Suppression: Institutional acquirers and private equity buyers normalize balance sheets. Capital trapped in non-operating cash is stripped out during valuation, whereas deployed capital that drove compound EBITDA expands the valuation multiple.
- Tax Inefficiency Under Corporate Rates: Holding passive income-generating deposits inside a trading entity subject to the standard 30% corporate tax rate (or 25% base rate entity threshold) yields poor post-tax capital accumulation compared to reinvestment into qualifying depreciable assets or dividend distributions.
- The Moral Hazard of Operational Slack: Abundant balance sheet cash routinely masks working capital discipline failures, extending Days Sales Outstanding (DSO) and weakening creditor terms management across procurement.
The True Cost of Defensive Capital
An FCPA analysis on structural liquidity drag
Carrying surplus cash reserves beyond calculated operational stress thresholds does not protect a mid-market enterprise; it imposes a continuous, unpriced penalty on Return on Invested Capital (ROIC). When directors allow substantial cash buffers to sit idle in commercial deposit accounts earning nominal yields below the weighted average cost of capital (WACC), they dilute equity performance and destroy economic value added (EVA). Principal Advisor Graham Chee (FCPA, CPA) draws on Fellow CPA Australia status and institutional governance frameworks to provide mid-market directors with clear, objective criteria to separate genuine solvency reserves from capital inefficiency.
Under Corporations Act 2001 (Cth) s 588G, Australian directors operate under strict statutory obligations to prevent insolvent trading. In the mid-market—enterprises typically reporting annual revenues between $10 million and $250 million—this fiduciary anxiety often manifests as perpetual over-hedging. Boards routinely hold between 90 and 180 days of operating expenses in cash or at-call deposits strategic commercial debt structuring and liquidity management. While this provides psychological comfort against external volatility, it ignores the fundamental corporate finance reality governed by AASB 107 Statement of Cash Flows: cash is an asset with a high opportunity cost. If an enterprise carries a WACC of 11% while maintaining $8 million in unencumbered cash yielding 4.25% pre-tax, the business incurs an annual structural negative spread of over 6.75% on that tranche. That drag lowers group ROIC and depresses multi-year business valuations.
Core Governance Realities
Five principles every director must evaluate regarding balance sheet cash
The Negative Spread Reality: Retaining idle liquidity when the corporate cost of capital exceeds short-term deposit yields actively destroys shareholder equity on an inflation-adjusted, post-tax basis.
Statutory Solvency versus Excess Buffers: Compliance with ASIC regulatory guidelines and s 588G requires demonstrable liquidity through structured access to capital, not exclusively static cash hoarding on the balance sheet.
M&A and Valuation Multiple Suppression: Institutional acquirers and private equity buyers normalize balance sheets. Capital trapped in non-operating cash is stripped out during valuation, whereas deployed capital that drove compound EBITDA expands the valuation multiple.
Tax Inefficiency Under Corporate Rates: Holding passive income-generating deposits inside a trading entity subject to the standard 30% corporate tax rate (or 25% base rate entity threshold) yields poor post-tax capital accumulation compared to reinvestment into qualifying depreciable assets or dividend distributions.
The Moral Hazard of Operational Slack: Abundant balance sheet cash routinely masks working capital discipline failures, extending Days Sales Outstanding (DSO) and weakening creditor terms management across procurement.
Systematised Capital Allocation Frameworks
Transitioning from defensive hoarding to dynamic liquidity architecture
A mature mid-market treasury framework replaces static liquidity balances with a multi-tiered liquidity architecture. The primary operational layer should service precisely 30 to 45 days of predictable operating expenditure, modelled against empirical receivables volatility and payroll obligations governed by Fair Work and modern award timing. Retaining liquidity beyond this operational horizon inside transaction accounts directly depresses the asset turnover component of the DuPont formula, dampening return on equity (ROE).
To manage macro uncertainty without sacrificing ROIC, Australian boards should establish structured contingent liquidity. This entails securing committed, undrawn credit lines, receivables financing facilities, or asset-backed reserves through tier-one or tier-two Australian banking institutions dynamic capital deployment and growth frameworks. A committed undrawn facility provides the legal and operational coverage required by ASIC solvency surveillance, yet converts a permanent drag on capital into a defined, predictable facility commitment fee. Directors maintain compliance with their statutory duty of care under s 180 of the Corporations Act while liberating operational surplus capital for organic growth, strategic acquisitions, or targeted return of capital to equity holders.
A Principal-Led Allocation Roadmap
Four disciplined stages to eliminate structural cash drag
Quantify Structural Working Capital Baselines
Calculate the precise peak-to-trough cash requirements over trailing 36-month cycles, identifying true operational minimums versus unallocated buffers.
Establish Tiered Liquidity Architecture
Segregate liquid capital into operational working capital (30-45 days), strategic opportunity reserves, and committed secondary facilities.
Formulate Hurdle-Rate Governance Policies
Institute a board-approved treasury policy where unallocated capital must either beat the corporate WACC threshold or be systematically released.
Conduct Quarterly Capital Efficiency Reviews
Subject the balance sheet to FCPA-level reviews alongside monthly management accounts to confirm liquidity targets remain aligned with growth cycles.
Director FAQs on Liquidity and Governance
Direct responses to key corporate finance and solvency inquiries
Q.Does holding a smaller cash buffer increase director liability under s 588G insolvent trading provisions?
No. Australian insolvency jurisprudence and ASIC guidance establish that solvency is a function of cash-flow capacity over time, not purely static cash held at bank. A company is solvent if it can pay its debts as and when they fall due. A robust, rolling 13-week systematised cash-flow model supported by committed undrawn banking facilities fulfills director duties far more effectively than an unmanaged, static cash reserve.
Q.What is the recommended operational cash reserve for an Australian mid-market business?
For businesses with stable, recurring revenue and established supplier terms, 30 to 45 days of operational expenses is standard. Companies exposed to project-based lumpy billing or substantial supply chain variability may require 60 days. Beyond 60 days, liquidity should be maintained through revolving credit arrangements rather than idle capital balances.
Q.How does idle cash specifically depress business enterprise value during an exit or capital raise?
Transaction advisors and institutional buyers price businesses on a multiple of sustainable earnings before interest, tax, depreciation, and amortisation (EBITDA), assuming a normalized level of working capital. Excess cash is simply treated as surplus cash returned to vendors at a 1:1 dollar value. Reinvesting that same capital into operational capacity, sales expansion, or operational efficiency that permanently increases EBITDA creates value multiplied by the transaction rating.
Q.How should seasonal working capital spikes be managed without holding perpetual excess cash?
Seasonal capital peaks should be addressed using self-liquidating facilities, such as selective invoice financing or structured working capital lines tied directly to debtor growth. This ensures borrowing costs are incurred exclusively during revenue expansion phases, rather than carrying the ROIC drag of permanent cash holdings throughout the entire fiscal year.
About the Author
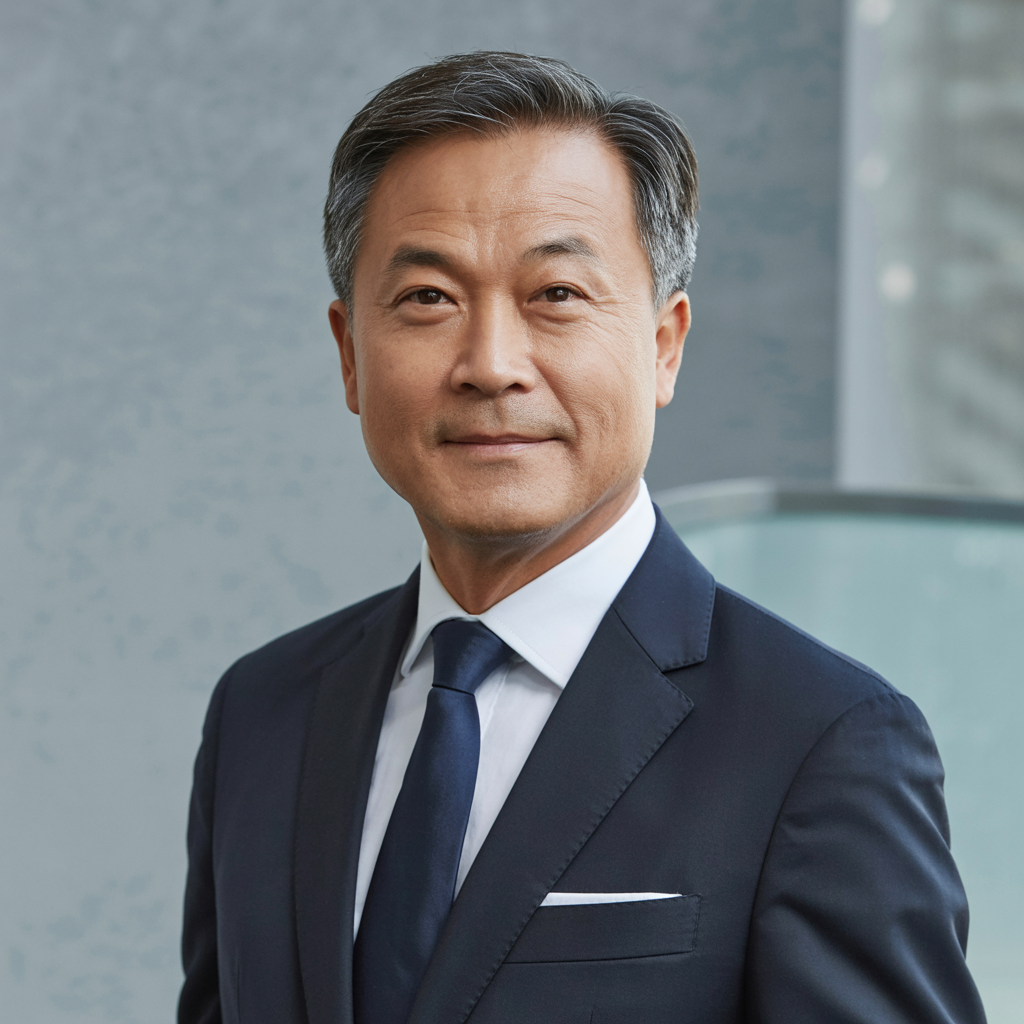
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.
Speak with an Advisor on Capital Allocation
The information presented in this article is for educational and strategic governance purposes only and does not constitute formal corporate, legal, or financial advice. Mid-market boards should engage professional counsel to assess their specific circumstances under Australian corporate law.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files