Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed October 2026. Next review scheduled for December 2026.
TL;DR
Defending earnings multiples, restructuring working capital pegs, and de-risking unapproved variations prior to an M&A exit or partner buyout.
Key Takeaways
- SOPA Reference Dates and AASB 15 Compliance: Revenue recognised on unapproved variations that lack an enforceable statutory reference date under Section 8 of the NSW SOPA must be normalised out of adjusted EBITDA under AASB 15 criteria, preventing aggressive buyer write-backs during financial due diligence.
- Treatment of Retentions as Long-Term Working Capital: Standard 5 percent to 10 percent retention funds withheld on tier-one builder head contracts must be segregated between current operating working capital and non-operating, high-risk assets, particularly where defects liability periods span 12 to 24 months across Sydney commercial towers.
- Statutory Payment Schedules as Hard Valuation Evidence: Uncontested payment claims under Section 14 of the NSW SOPA carry statutory debt status, providing verifiable balance sheet strength; conversely, persistent unresolved Section 17 adjudication applications must be factored into earnings volatility adjustments.
- Subcontractor Trust Requirements: For projects valued above 20 million dollars under the NSW Building and Construction Security of Payment Amendment, retention money trust account obligations impose strict compliance liabilities that directly affect debt-free, cash-free completion accounts.
- Normalisation of Discretionary and Related-Party Plant Leasing: Heavy civil and trade contractors frequently distort operating EBITDA via internal plant hire entities or non-commercial yard leases across Western Sydney; establishing market-rate adjustments is mandatory to validate true maintainable earnings.
The Strategic Multiplier Risk in Subcontractor Valuations
Why standard EBITDA fails without statutory balance sheet normalisation
For Sydney engineering, civil, and mechanical subcontractors, enterprise value is routinely degraded during acquisition due diligence when Work-in-Progress (WIP) and retention ledgers are improperly documented. To defend an earnings multiple in an M&A transaction or partner buyout, enterprise owners must systematically normalise unapproved variations and retention receivables under the strict statutory mechanics of the NSW Building and Construction Industry Security of Payment Act 1999 (SOPA). Failure to separate true operating earnings from statutory payment dispute exposure leaves vendors vulnerable to severe working capital target adjustments and debt-like item write-downs.
Principal Advisor Graham Chee (FCPA, CPA) draws on Fellow CPA Australia status and prior institutional roles to examine how Sydney trade and civil subcontractors must normalise cash flow, retentions, and unapproved variations under the NSW Building and Construction Industry Security of Payment Act to defend earnings multiples ahead of an M&A exit or partner buyout rigorous Australian business valuation methods. From our principal-led practice in Mascot, operating under the CPA Code of Ethics since 2003, we observe Sydney CBD, North Shore infrastructure, and Western Sydney Airport transport corridor contractors forfeit substantial transaction value. Valuers and institutional acquirers do not price subcontracting businesses on headline revenue; they price certainty of cash conversion and downside risk.
Key Valuation and Balance Sheet Considerations
Navigating statutory reality versus paper earnings
SOPA Reference Dates and AASB 15 Compliance: Revenue recognised on unapproved variations that lack an enforceable statutory reference date under Section 8 of the NSW SOPA must be normalised out of adjusted EBITDA under AASB 15 criteria, preventing aggressive buyer write-backs during financial due diligence.
Treatment of Retentions as Long-Term Working Capital: Standard 5 percent to 10 percent retention funds withheld on tier-one builder head contracts must be segregated between current operating working capital and non-operating, high-risk assets, particularly where defects liability periods span 12 to 24 months across Sydney commercial towers.
Statutory Payment Schedules as Hard Valuation Evidence: Uncontested payment claims under Section 14 of the NSW SOPA carry statutory debt status, providing verifiable balance sheet strength; conversely, persistent unresolved Section 17 adjudication applications must be factored into earnings volatility adjustments.
Subcontractor Trust Requirements: For projects valued above 20 million dollars under the NSW Building and Construction Security of Payment Amendment, retention money trust account obligations impose strict compliance liabilities that directly affect debt-free, cash-free completion accounts.
Normalisation of Discretionary and Related-Party Plant Leasing: Heavy civil and trade contractors frequently distort operating EBITDA via internal plant hire entities or non-commercial yard leases across Western Sydney; establishing market-rate adjustments is mandatory to validate true maintainable earnings.
Defending the Working Capital Peg: In an M&A completion accounts mechanism, an uncalibrated normalisation of trade debtors and accrued revenue will result in an arbitrary peg set by the acquirer, causing dollar-for-dollar deductions from the final purchase price.
Structuring Enterprise Value for an Exit or Buyout
Translating contractual mechanics into bankable balance sheet protection
The real question is not what your profit and loss statement reports, but whether your trade working capital is backed by ironclad statutory leverage. In middle-market Sydney transactions—whether resolving an equity partner succession across a civil works outfit in North Sydney or executing a partial trade sale to an interstate contractor—acquirers scrutinise the ageing of WIP and accrued revenues. Under AASB 15 (Revenue from Contracts with Customers), variable consideration cannot be recognised unless it is highly probable that a significant reversal will not occur. In the context of NSW civil infrastructure, unapproved variation claims sitting in WIP without formal Section 13 payment claim support are routinely categorised by forensic auditors as speculative contingencies, leading to severe EBITDA haircuts.
To position a trade or engineering firm for maximum leverage at sale, the entity design must isolate project risks. Commercial contracts executed across Greater Sydney routinely attempt to extinguish or limit statutory claim timelines specialist Sydney accounting advisors. However, because Section 34 of the NSW SOPA voids contract terms designed to exclude the Act, sophisticated vendors use this statutory backstop to defend balance sheet recoverability. Normalising your earnings involves categorising receivables into three clear tiers: certified claims backed by unissued or uncontested schedules, formal claims currently undergoing statutory adjudication, and disputed unapproved variations. By systematically auditing the historical conversion velocity of these buckets over a 36-month period, we demonstrate maintainable margin stability, protect the vendor against retrospective warranty claims, and secure an optimal after-tax outcome under the Australian capital gains tax (CGT) small business concessions.
The Strategic Normalisation Methodology
A principal-led approach to defending subcontractor transaction value
AASB 15 and SOPA Audit
Perform a line-item reconciliation of accrued WIP against valid reference dates under Section 8 of the NSW Act to eliminate unrecoverable margin claims.
Retention Ledger De-Risking
Segregate retentions into statutory trust-compliant buckets and perform solvency assessments on head contractors across all active Sydney projects.
EBITDA Normalisation
Adjust operating statements for non-market yard rentals, owner-operator personal remuneration, and related-party plant leasing rates.
Working Capital Peg Defence
Model a defendable 12-month rolling target working capital metric to prevent completion account purchase price erosion during legal completion.
Frequently Asked Valuation Questions
Commercial insights for Sydney construction and trade directors
Q.How do acquirers treat retentions held on Sydney commercial construction projects?
Institutional buyers typically categorise retentions due past 12 months as non-working capital assets or apply a risk discount of 15 to 30 percent, particularly if linked to commercial head contractors facing insolvency risk. To preserve transaction value, retentions must be matched with formal practical completion certificates and documented defect period expiries. capital structuring and buyout financing strategies
Q.Can unapproved variations be included in adjusted EBITDA for valuation purposes?
Generally, no, unless they satisfy the enforceable rights threshold under AASB 15 and comply with Section 13 payment claim procedures under NSW SOPA. Valuers will normalise unapproved variations out of EBITDA unless the vendor can demonstrate an institutional history of recovering these claims at adjudication or through executed variation orders.
Q.What is the consequence of failing to normalise related-party plant hire entities?
Operating civil earthmoving or heavy engineering subcontractors often run plant hire through separate family trusts at above-market rates. If this is not normalised to commercial market rates prior to market entry, the buyer's advisory team will adjust operating expenses upward, directly depressing normalised EBITDA and destroying multiple-based enterprise value.
Q.How does the working capital peg impact the cash proceeds received at settlement?
The working capital peg sets the baseline expectation of operational liquidity included in the enterprise sale price. If your WIP or retentions are deemed overstated or stale during completion accounting, net working capital will fall below the peg, resulting in an unhedged, dollar-for-dollar deduction from the cash paid at settlement.
About the Author
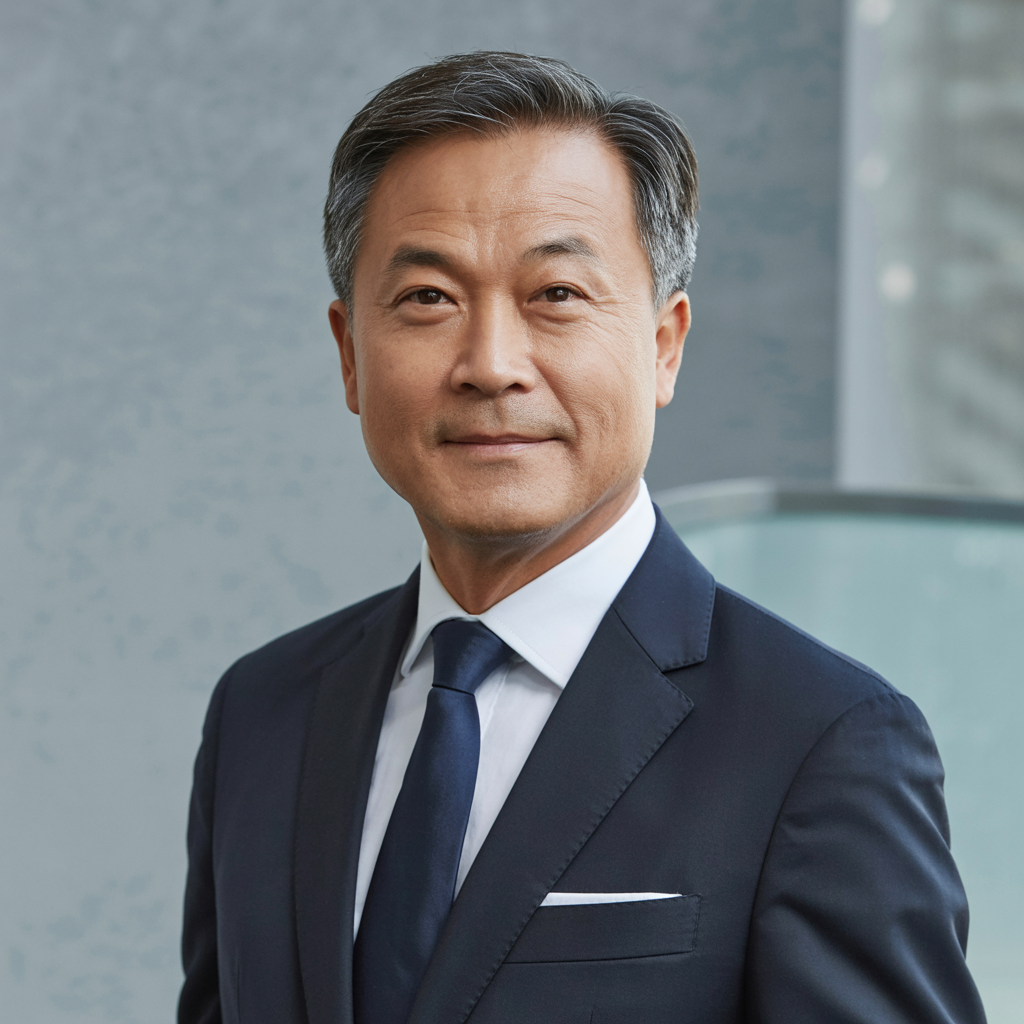
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.
Get Expert Guidance - Contact Our Principal Practice
This analysis provides strategic advisory commentary and does not constitute formal legal or transactional advice. Subcontracting businesses require individual evaluation under NSW legislation and applicable accounting standards.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files