3 Critical Cash Flow Myths Sydney SMEs Still Believe
Understand the misconceptions that can place a profitable business under financial pressure, and learn practical ways to improve cash flow visibility and control. Sydney accounting and cash flow support
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed November 2026. Next review scheduled for February 2027.
TL;DR
Understand the misconceptions that can place a profitable business under financial pressure, and learn practical ways to improve cash flow visibility and control. [Sydney accounting and cash flow support](https://www.sydney.accountants)
Key Takeaways
- Myth 1: Profit means cash is available. Profit is an accounting result, while cash flow reflects when money is actually received and paid. Revenue may be recognised before a customer pays, and cash may be committed to stock, equipment, loan repayments or tax liabilities.
- Myth 2: A healthy bank balance means the business can afford to spend. Part of the balance may be needed for GST, PAYG withholding, superannuation, payroll, rent, supplier invoices or debt repayments. The current balance should be considered alongside upcoming obligations.
- Myth 3: More sales will automatically solve cash flow problems. Growth can increase pressure when materials, labour and operating costs must be paid before customers settle their invoices. Rapid growth without suitable pricing, payment terms and working capital can deepen a cash shortfall.
- Timing is as important as total income and expenditure. A business may generate enough revenue over a quarter but still experience a critical weekly funding gap because receipts arrive after major payments are due.
- Accounts receivable and inventory are not the same as cash. Overdue invoices and slow-moving stock can make the balance sheet appear stronger without providing the liquidity needed for immediate commitments.
Introduction
Why cash flow misconceptions matter
This analysis on debunking common cash flow management misconceptions that can lead to distress for Sydney small businesses is written by Graham Chee, FCPA, CPA, GRCP, GRCA — Fellow of CPA Australia since November 2005, continuous CPA member since 1986, and principal of Local Knowledge. Based in Mascot, NSW, Local Knowledge has operated as a principal-led practice since 2003, with FCPA sign-off on every file and professional work guided by the CPA Code of Ethics. Cash flow difficulties do not affect only unprofitable businesses build a practical cash flow forecast. A business can report a profit, win new work and maintain a positive bank balance while still being unable to meet payroll, supplier, tax or finance commitments when they fall due. This article explains three persistent cash flow myths and the practical controls Sydney SMEs can use to make better-informed decisions.
Key Concepts
Six essential points for business owners and managers
Myth 1: Profit means cash is available. Profit is an accounting result, while cash flow reflects when money is actually received and paid. Revenue may be recognised before a customer pays, and cash may be committed to stock, equipment, loan repayments or tax liabilities.
Myth 2: A healthy bank balance means the business can afford to spend. Part of the balance may be needed for GST, PAYG withholding, superannuation, payroll, rent, supplier invoices or debt repayments. The current balance should be considered alongside upcoming obligations.
Myth 3: More sales will automatically solve cash flow problems. Growth can increase pressure when materials, labour and operating costs must be paid before customers settle their invoices. Rapid growth without suitable pricing, payment terms and working capital can deepen a cash shortfall.
Timing is as important as total income and expenditure. A business may generate enough revenue over a quarter but still experience a critical weekly funding gap because receipts arrive after major payments are due.
Accounts receivable and inventory are not the same as cash. Overdue invoices and slow-moving stock can make the balance sheet appear stronger without providing the liquidity needed for immediate commitments.
Cash flow management is forward-looking. Historical financial statements remain important, but a regularly updated rolling forecast is needed to identify future pressure points and allow time for corrective action.
Practical Guidance
How the three myths appear in real business situations
Consider a Sydney service business that completes a large project and records the invoice as revenue. Its profit and loss statement may show a positive result, but if the customer has 30-day terms and pays late, the business may have to fund wages, subcontractors, rent and GST before receiving the cash. This demonstrates why profit is not the same as liquidity.
A positive bank balance can also create false confidence. For example, a manager may approve equipment purchases because sufficient funds appear to be available. If a significant portion of that money is effectively reserved for payroll, superannuation, BAS obligations and supplier payments due the following week, the purchase may leave the business exposed. Separating tax funds and maintaining a short-term commitments schedule can provide a more realistic view of available cash.
Growth can produce similar pressure. A retailer, wholesaler or trade business may accept more orders but need to purchase inventory or materials in advance broader financial strategy insights. A professional services firm may add employees before new client invoices are collected. In both cases, sales can rise while cash falls. Owners should examine gross margin, customer payment behaviour, supplier terms, capacity costs and the length of the cash conversion cycle before committing to expansion.
Experienced cash flow management connects operational decisions with financial timing. Useful practices include issuing invoices promptly, confirming payment terms before work begins, following up overdue accounts consistently, negotiating appropriate deposits or progress payments, reviewing stock levels, and maintaining a rolling forecast. Forecasts should include realistic collection dates rather than assuming every invoice will be paid on time. They should also account for irregular obligations such as tax payments, insurance renewals, annual subscriptions, equipment costs and seasonal fluctuations.
Recommended Steps
A structured approach to improving cash flow control
Assess
Review current bank balances, unpaid customer invoices, supplier commitments, payroll, tax liabilities, debt repayments and other upcoming expenses. Distinguish unrestricted cash from money already committed.
Forecast
Prepare a rolling cash flow forecast using realistic payment and collection dates. Test different scenarios, including delayed customer payments, reduced sales, cost increases or planned growth.
Act
Address identified gaps early. Actions may include improving invoicing and collection procedures, revising payment terms, requesting deposits, managing stock, reviewing expenditure or discussing finance requirements with appropriate advisors.
Review
Compare forecast figures with actual cash movements regularly. Investigate material differences, update assumptions and adjust operational decisions before a temporary shortfall becomes a more serious problem.
Common Questions
What Sydney business owners often ask about cash flow
Q.How can my business be profitable but still run out of cash?
Profit includes income earned and expenses incurred, regardless of whether the associated cash has been received or paid. Slow customer payments, inventory purchases, loan principal repayments, asset purchases and tax obligations can consume cash without appearing in the same way on the profit and loss statement.
Q.How often should I update a cash flow forecast?
The appropriate frequency depends on the level of risk and transaction activity. Many SMEs benefit from reviewing near-term cash flow weekly and extending the forecast over a longer planning period. A business facing tight liquidity may need more frequent monitoring.
Q.Should GST and PAYG withholding be treated as available cash?
Generally, amounts collected or withheld for tax obligations should not be treated as unrestricted operating cash. Keeping these commitments visible, and potentially separating funds where appropriate, can reduce the risk of spending money needed for future lodgements and payments.
Q.Can increasing prices improve cash flow?
Appropriate pricing may improve margins and cash generation, but pricing should be considered together with customer demand, service costs, payment terms and collection speed. A price increase will not solve cash flow pressure if invoices remain unpaid or costs rise faster than revenue.
Q.When should I seek professional guidance?
Seek guidance early if forecasts show an upcoming shortfall, tax or supplier obligations are becoming difficult to meet, receivables are ageing, or growth requires more working capital than expected. Earlier analysis generally provides more options than waiting until payments are overdue.
Conclusion
Replace assumptions with informed cash flow decisions
Profit, bank balances and sales growth each provide useful information, but none offers a complete picture of financial capacity. Sydney SMEs need to understand when cash will enter the business, when obligations must be paid and how operational decisions affect working capital. A realistic forecast, disciplined collection procedures and regular review can help owners identify pressure before it becomes distress. For guidance tailored to your business structure, commitments and objectives, contact our team and speak with an advisor.
About the Author
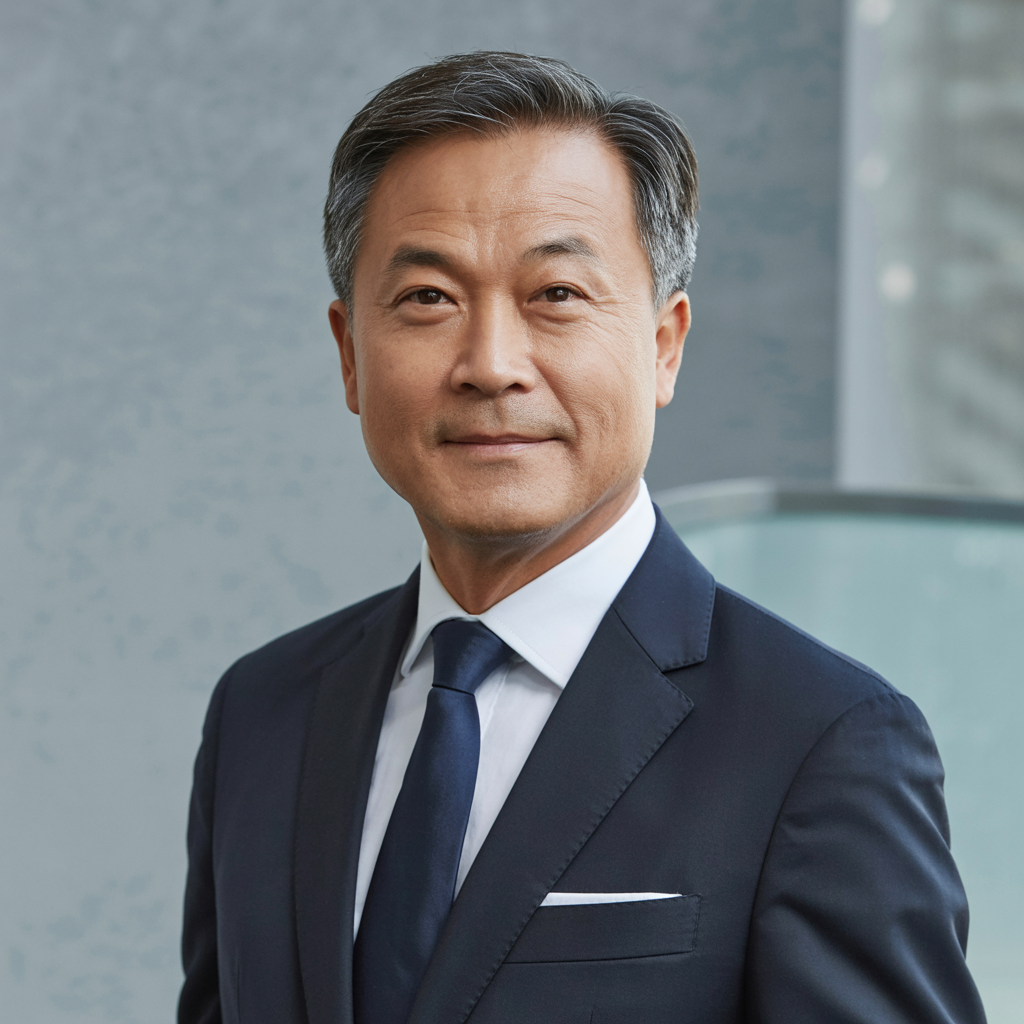
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.
Get Expert Guidance — Contact Our Team
Every business situation is unique. This article provides general educational information and does not replace advice based on your specific financial, legal or tax circumstances.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files