Strategic Accounting and Advisory for Ryde Business Owners
Principal-led corporate tax structuring, entity design, and board-level advisory for established enterprises across Ryde and the Northern Suburbs. corporate tax structuring and entity design
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed October 2026. Next review scheduled for January 2027.
TL;DR
Principal-led corporate tax structuring, entity design, and board-level advisory for established enterprises across Ryde and the Northern Suburbs. [corporate tax structuring and entity design](/insights/business-structure-tax-efficiency)
Key Takeaways
- Entity Architecture and Risk Ring-Fencing: Structuring trading entities, intellectual property holding companies, and discretionary or unit trusts to shield active operating risks from core commercial and property assets.
- Corporate Tax and Base Rate Entity Optimization: Managing active business income test parameters under Section 23AA to access the 25% base rate entity corporate tax rate rather than the 30% baseline, while methodically tracking franking account balances.
- Division 7A and Private Company Governance: Systematising shareholder loans, distributable surplus calculations, and formal complying loan agreements to prevent deemed unfranked dividends under Section 109N.
- Statutory Payroll and Superannuation Guarantee Compliance: Rigorous alignment with Fair Work modern awards and Superannuation Guarantee compliance under the 11.5% statutory rate (increasing to 12% on 1 July 2025), structured ahead of upcoming Payday Super mandates.
- Capital Gains Tax and Commercial Property Positioning: Utilizing Division 152 small business CGT concessions alongside the general 50% discount to protect proceeds upon business divestment or commercial premises restructuring.
Principal-Led Strategic Advisory in Ryde
Beyond compliance box-ticking to capital protection and tax positioning
For mid-market enterprises, commercial property holders, and expanding tech operations across the Ryde precinct, routine bookkeeping fails to protect enterprise value. Ryde businesses require sophisticated entity design, stringent ATO compliance, and proactive capital positioning that safeguard working capital and mitigate downside commercial exposure. Graham Chee, FCPA, CPA, principal of Local Knowledge, writes from a practice that pairs FCPA-grade compliance with Goldman Sachs, BNP Investment Management and Merrill Lynch institutional experience on delivering principal-led tax and advisory solutions for Ryde businesses and the broader Sydney metropolitan market.
Operating through Local Knowledge Pty Ltd—a CPA public practice and registered tax agent established in 2003—we ensure every ledger, restructuring plan, and corporate lodgement receives senior FCPA review specialist Sydney accounting and advisory networks. Situated between the Macquarie Park innovation corridor, the traditional commercial centres of Church Street, and the arterial connections of Devlin Street and Victoria Road, Ryde companies operate in high-value, highly visible sectors. Navigating this landscape requires seasoned commercial counsel that treats accounting not as a historical recording exercise, but as a lever for after-tax returns, corporate resilience, and seamless wealth succession.
Core Strategic Priorities for Ryde Directors
Key structural and regulatory considerations for growing mid-tier firms
Entity Architecture and Risk Ring-Fencing: Structuring trading entities, intellectual property holding companies, and discretionary or unit trusts to shield active operating risks from core commercial and property assets.
Corporate Tax and Base Rate Entity Optimization: Managing active business income test parameters under Section 23AA to access the 25% base rate entity corporate tax rate rather than the 30% baseline, while methodically tracking franking account balances.
Division 7A and Private Company Governance: Systematising shareholder loans, distributable surplus calculations, and formal complying loan agreements to prevent deemed unfranked dividends under Section 109N.
Statutory Payroll and Superannuation Guarantee Compliance: Rigorous alignment with Fair Work modern awards and Superannuation Guarantee compliance under the 11.5% statutory rate (increasing to 12% on 1 July 2025), structured ahead of upcoming Payday Super mandates.
Capital Gains Tax and Commercial Property Positioning: Utilizing Division 152 small business CGT concessions alongside the general 50% discount to protect proceeds upon business divestment or commercial premises restructuring.
Systematised BAS and Executive Lodgements: Securing tax agent extensions and robust quarterly lodgement frameworks across business activity statements, Single Touch Payroll (STP) Phase 2, and annual ASIC corporate registers.
Practical Application: Navigating Growth and Commercial Exposure
Managing liquidity, Division 7A, and restructuring trade-offs in real commercial scenarios
Consider an established engineering or commercial services enterprise based in Ryde generating between $3 million and $15 million in turnover. The business frequently encounters working capital constraints due to lengthy project milestones, coupled with significant cash outflows for quarterly PAYG instalments and payroll taxes. The real question is: does the existing structure facilitate working capital reinvestment, or does it leak tax efficiency through poorly planned director loan drawings?
Without a systematised approach to Division 7A, informal inter-company loans between trading arms and property-holding entities risk triggering severe deemed dividend assessments under ATO scrutiny commercial capital and cash flow strategies. We engineer principal-led restructuring strategies that utilise corporate beneficiaries, bucket companies, and formalised 7-year or 25-year secured loan arrangements under Section 109N. Furthermore, for owners holding commercial freeholds in industrial precincts such as Ryde or Gladesville, separating property title from trading operations via discretionary trusts with corporate trustees provides reasonable assurance of asset protection against commercial litigation, while maximizing small business CGT concessions upon retirement or exit.
The Strategic Advisory Framework
A disciplined, four-stage approach to corporate tax and financial control
Entity Diagnostics
Comprehensive audit of existing corporate, trust, and partnership structures to identify asset exposure, Division 7A vulnerabilities, and untapped tax concessions.
Structural Alignment
Redesigning inter-entity flows, corporate governance charters, and franking credit strategies to retain working capital at optimal corporate tax rates.
Systematised Lodgement
Executing continuous statutory compliance including quarterly BAS, STP Phase 2, corporate tax returns, and ASIC director declarations under strict CPA standards.
CFO Strategic Review
Ongoing executive-level advisory evaluating balance sheet health, downstream capital gains outcomes, and succession readiness before key fiscal milestones.
Strategic Questions Ryde Directors Ask
Incisive answers to complex accounting and regulatory concerns
Q.How does our business qualify for the 25% corporate tax rate instead of 30%?
To access the 25% base rate entity corporate tax rate for the current financial year, your company must have an aggregated annual turnover below $50 million, and no more than 80% of its assessable income can be base rate entity passive income (such as interest, net dividends, or passive rent). We analyze your revenue composition each quarter to ensure active income ratios are maintained, preserving working capital for operational reinvestment.
Q.What are the common compliance triggers for ATO audits in the Northern Suburbs?
The ATO focuses heavily on unexplained lifestyle assets relative to reported taxable income, unmanaged Division 7A director loans, excessive commercial motor vehicle depreciation claims under the instant asset write-off thresholds, and delays in Superannuation Guarantee contributions. Our practice applies rigorous pre-lodgement review frameworks that provide reasonable assurance of full evidentiary substantiation before submissions are made.
Q.Why is separating commercial property from the operating entity critical?
Operating a business out of an entity that also owns the underlying commercial freehold exposes the real estate to creditors, product liability, and employment claims. Holding the property in a dedicated trust or distinct asset entity, leased on arms-length commercial terms to the trading company, shields the asset from operational liabilities while securing capital gains tax positioning for future succession or asset realization.
Q.How do you manage company and trust taxation across the broader Sydney area?
From our principal office in Mascot, Local Knowledge serves established corporate clients throughout Ryde, the Sydney CBD, the North Shore, and the Eastern Suburbs. While client financial platforms are systematised for secure digital collaboration, every file, tax calculation, and advisory plan is directly overseen and signed off by an FCPA principal.
About the Author
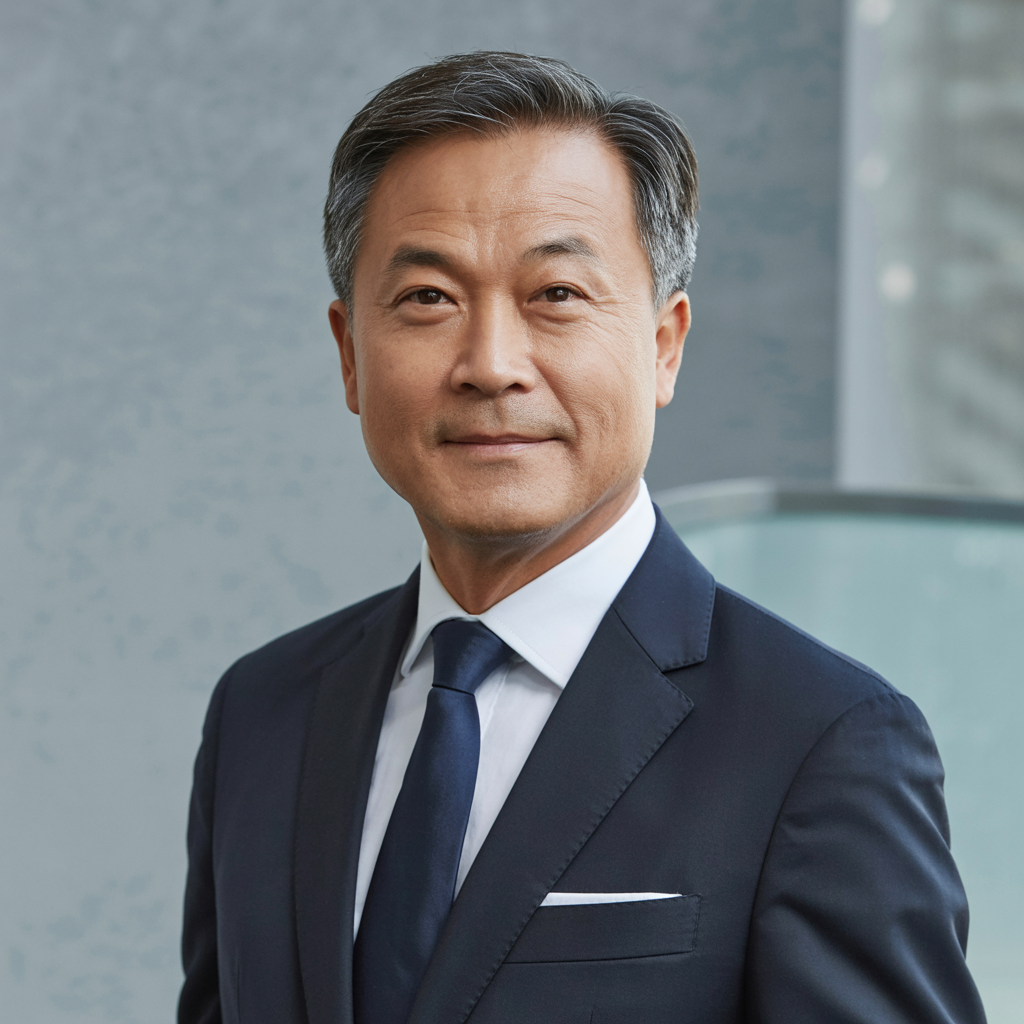
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.
Get Expert Guidance
Local Knowledge Pty Ltd is a CPA Practice and Registered Tax Agent. Information provided in this article is general educational commentary and does not constitute individual legal, tax, or financial advice. Engagements are tailored to specific corporate circumstances under a formal letter of engagement.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files