BAS & GST Lodgement in Newtown: What Business Owners Need to Know
If your Newtown business is GST-registered, its BAS must report GST and any applicable PAYG obligations by the ATO due date. Local Knowledge Pty Ltd provides principal-led BAS and GST preparation, review and lodgement so your figures are checked, your deadlines are clear and your business can stay on top of cash flow. Sydney accounting support for small businesses
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed October 2026. Next review scheduled for January 2027.
TL;DR
If your Newtown business is GST-registered, its BAS must report GST and any applicable PAYG obligations by the ATO due date. Local Knowledge Pty Ltd provides principal-led BAS and GST preparation, review and lodgement so your figures are checked, your deadlines are clear and your business can stay on top of cash flow. [Sydney accounting support for small businesses](https://www.sydney.accountants)
Key Takeaways
- The GST turnover threshold is $75,000. A business generally needs to become GST-registered when its current or projected GST turnover reaches $75,000. GST turnover is not always the same as bank deposits or accounting profit, and the ATO generally requires action within 21 days after the business becomes required to register. The threshold for a non-profit body is $150,000. Taxi and ride-sourcing drivers have separate rules and generally need GST registration regardless of turnover. Source: Australian Taxation Office, Registering for GST.
- Most smaller GST-registered businesses lodge quarterly. For the 2025–26 financial year, the standard quarterly BAS due dates are 28 October 2025 for July to September, 28 February 2026 for October to December, 28 April 2026 for January to March, and 28 July 2026 for April to June. If a due date falls on a weekend or public holiday, lodgement and payment can generally be made on the next business day. For example, 28 February 2026 falls on a Saturday, so the next business day is Monday 2 March 2026. Source: ATO, Due dates for lodging and paying your BAS.
- Monthly GST reporting is generally required when GST turnover is $20 million or more. Some smaller businesses choose monthly reporting, but it creates 12 reporting cycles instead of four. A monthly activity statement is normally due on the 21st day of the following month, subject to the ATO weekend and public holiday rule. Source: ATO, GST reporting methods.
- PAYG withholding is money withheld from payments such as employee wages and certain contractor payments. Small withholders, generally those withholding $25,000 or less a year, usually pay quarterly. Medium withholders, generally from $25,001 to $1 million, usually pay monthly. Large withholders above $1 million have more frequent payment obligations determined by the ATO. These obligations are separate from super and Single Touch Payroll reporting.
- PAYG instalments are prepayments towards the expected income tax of a business or individual. They are not the same as PAYG withholding from wages. The ATO may place a business into the PAYG instalment system and show either an instalment amount or instalment rate on the activity statement. Quarterly instalments usually follow the BAS due dates, while some eligible taxpayers may receive an annual option.
BAS lodgement without the last-minute stress
Practical guidance for Newtown business owners and directors
BAS can become stressful when the bank feed is behind, payroll does not match Single Touch Payroll, or you are unsure which purchases include GST. The good news is that the process can be handled step by step: keep the books current, reconcile the key accounts, review the GST treatment and lodge by the correct Australian Taxation Office deadline.
Graham Chee, FCPA, CPA, GRCP, GRCA, principal of Local Knowledge, writes from a practice that pairs FCPA-grade compliance with Goldman Sachs, BNP Investment Management and Merrill Lynch institutional experience. Local Knowledge Pty Ltd, based in Mascot and established in 2003, is the operating entity behind this service. It is a CPA public practice and registered tax agent—not a separate Newtown business.
The service is principal-led, with FCPA sign-off on every file. Work is carried out under the CPA Code of Ethics and APES 110 Code of Ethics for Professional Accountants. Our review is designed to provide reasonable assurance that the BAS agrees with the available records and has been treated consistently with current ATO requirements.
Newtown has a distinctive business mix bookkeeping support for BAS, GST and payroll. A King Street cafe may deal with delivery platforms, cash sales and casual payroll. A retailer near Newtown Station may use several card terminals and sell both in-store and online. A sparky working on local terrace renovations may have vehicles, materials, subcontractors and progress invoices. Creative studios and growing startups around Newtown and Enmore often have software costs, overseas suppliers and contractor payments. Each business needs the same basic BAS cycle, but the bookkeeping details can be quite different.
Six BAS and GST points to understand
The thresholds, cycles and due dates that matter
The GST turnover threshold is $75,000. A business generally needs to become GST-registered when its current or projected GST turnover reaches $75,000. GST turnover is not always the same as bank deposits or accounting profit, and the ATO generally requires action within 21 days after the business becomes required to register. The threshold for a non-profit body is $150,000. Taxi and ride-sourcing drivers have separate rules and generally need GST registration regardless of turnover. Source: Australian Taxation Office, Registering for GST.
Most smaller GST-registered businesses lodge quarterly. For the 2025–26 financial year, the standard quarterly BAS due dates are 28 October 2025 for July to September, 28 February 2026 for October to December, 28 April 2026 for January to March, and 28 July 2026 for April to June. If a due date falls on a weekend or public holiday, lodgement and payment can generally be made on the next business day. For example, 28 February 2026 falls on a Saturday, so the next business day is Monday 2 March 2026. Source: ATO, Due dates for lodging and paying your BAS.
Monthly GST reporting is generally required when GST turnover is $20 million or more. Some smaller businesses choose monthly reporting, but it creates 12 reporting cycles instead of four. A monthly activity statement is normally due on the 21st day of the following month, subject to the ATO weekend and public holiday rule. Source: ATO, GST reporting methods.
PAYG withholding is money withheld from payments such as employee wages and certain contractor payments. Small withholders, generally those withholding $25,000 or less a year, usually pay quarterly. Medium withholders, generally from $25,001 to $1 million, usually pay monthly. Large withholders above $1 million have more frequent payment obligations determined by the ATO. These obligations are separate from super and Single Touch Payroll reporting.
PAYG instalments are prepayments towards the expected income tax of a business or individual. They are not the same as PAYG withholding from wages. The ATO may place a business into the PAYG instalment system and show either an instalment amount or instalment rate on the activity statement. Quarterly instalments usually follow the BAS due dates, while some eligible taxpayers may receive an annual option.
Lodgement and payment are separate obligations. A business should still lodge an accurate BAS by the due date even when cash flow is tight. The ATO may consider a payment plan, but interest can apply and approval is not guaranteed. Lodging on time also keeps the business record clearer for directors, lenders and year-end tax work.
How BAS works in a real Newtown business
From day-to-day transactions to a lodged activity statement
A BAS starts with the day-to-day books. Sales, expenses, payroll, bank transactions and merchant settlements need to be recorded for the correct period. We then reconcile the bank accounts, credit cards, loans, payroll reports and GST control accounts before preparing the activity statement.
Consider a King Street cafe using Square, Uber Eats and a business bank account. The delivery platform may deposit a net amount after taking fees, but the accounting records may need to show the gross sale, the platform fee and the GST treatment of each part. Recording only the net bank deposit can understate sales and produce the wrong GST result.
For a Newtown tradie, common issues include private use of the work vehicle, supplier invoices crossing BAS periods, transfers between accounts being coded as income, and materials bought without a valid tax invoice. The ATO generally requires a tax invoice to claim a GST credit for a taxable purchase above $82.50 including GST, subject to specific exceptions.
For a startup or creative studio, overseas software and digital services need attention. GST may not appear on every invoice, and an overseas charge should not be treated as containing Australian GST simply because it is a business expense how STP Phase 2 payroll reporting works. Director loans, owner contributions and transfers between accounts also do not automatically create GST.
Payroll needs its own checks. We compare the payroll ledger with Single Touch Payroll reports and the PAYG withholding shown on the activity statement. The ATO generally requires employers to report payroll information through Single Touch Payroll on or before payday, while Fair Work requires employee records to be kept for seven years. ASIC states that companies must keep sufficient financial records for seven years. These recordkeeping duties support accurate BAS, payroll and director oversight.
Common errors we fix include claiming GST on wages, super, loan repayments, bank transfers or residential rent; missing GST on taxable sales; treating GST-free or input-taxed items as taxable; duplicating transactions from bank feeds; recording merchant settlements as total sales; using the wrong cash or accrual basis; omitting cash takings; and carrying old GST coding errors from one quarter into the next.
Where a correction is needed, we assess whether it can be made on a later BAS under the ATO correction rules or whether a revision is required. We do not simply push a balancing figure into the next quarter without checking the cause.
Our step-by-step BAS process
A systematised approach to staying accurate and on time
Get the records up to date
We gather the accounting file, bank and credit card statements, sales reports, payroll records, finance statements and missing invoices. We also confirm whether the business reports GST on a cash or non-cash basis and whether it lodges monthly or quarterly.
Reconcile and check the details
We reconcile bank accounts, merchant services, payroll, PAYG withholding, loans and GST control accounts. Unusual or unclear transactions are raised with you in plain English rather than guessed.
Review and lodge
The BAS is reviewed with FCPA sign-off on every file. We explain the amount payable or refundable, obtain the required authority and lodge through the registered tax agent channel by the applicable ATO deadline.
Plan for the next due date
We confirm the next reporting period and expected deadline, then identify any bookkeeping or cash-flow items that need attention. Tax agent lodgement concessions may apply in some cases, but we confirm them from the current ATO lodgement program rather than assuming an extension.
BAS questions Newtown owners often ask
Clear answers to common day-to-day concerns
Q.My turnover is getting close to $75,000. What should I do?
Review both current and projected GST turnover rather than waiting for the bank balance to cross $75,000. The calculation can exclude some receipts, such as certain asset sales, while including taxable and GST-free business sales. Get advice early so you know whether GST registration is required and when prices, invoices and bookkeeping need to change.
Q.Should my Newtown business lodge quarterly or monthly?
Most businesses below $20 million in GST turnover report quarterly. Businesses at or above $20 million generally report monthly, and some smaller businesses choose monthly reporting. The right cycle depends on ATO requirements, cash flow, bookkeeping capacity and whether more frequent reporting would genuinely help.
Q.Can I claim GST on every business expense?
No. The purchase generally needs to be connected with the business, include GST and be supported by the required evidence. Wages, super, most bank fees, loan principal, residential rent and many overseas purchases do not include claimable GST. Mixed business and private costs may need to be apportioned.
Q.What if I cannot pay the BAS by the due date?
Lodge the BAS on time if possible, even when the full amount cannot be paid. This prevents the lodgement issue from becoming another problem. You can then discuss payment options with the ATO or your registered tax agent. General interest charge may apply, and any payment arrangement depends on ATO approval.
Q.I found an error in a BAS that has already been lodged. Can it be fixed?
Usually, yes. Depending on the amount, age and type of error, the correction may be included in a later activity statement or require a BAS revision. We first trace the error to the underlying transaction so the same problem does not continue into later periods.
Keep your next Newtown BAS sorted
Principal-led help from a CPA public practice
The easiest BAS is the one prepared from books that are already under control. Keep sales complete, reconcile accounts regularly, save valid tax invoices and set aside GST and PAYG amounts as part of normal cash-flow planning.
If your records are behind, the due date is close or a past BAS looks wrong, the next step is a calm review of what is complete and what is missing. Local Knowledge Pty Ltd can help with BAS preparation, GST reconciliation, PAYG reporting, corrections and lodgement for Newtown businesses.
Contact our team to speak with a principal-led, registered tax agent practice. We will explain what is needed, confirm the relevant ATO deadlines and provide guidance suited to your business circumstances.
About the Author
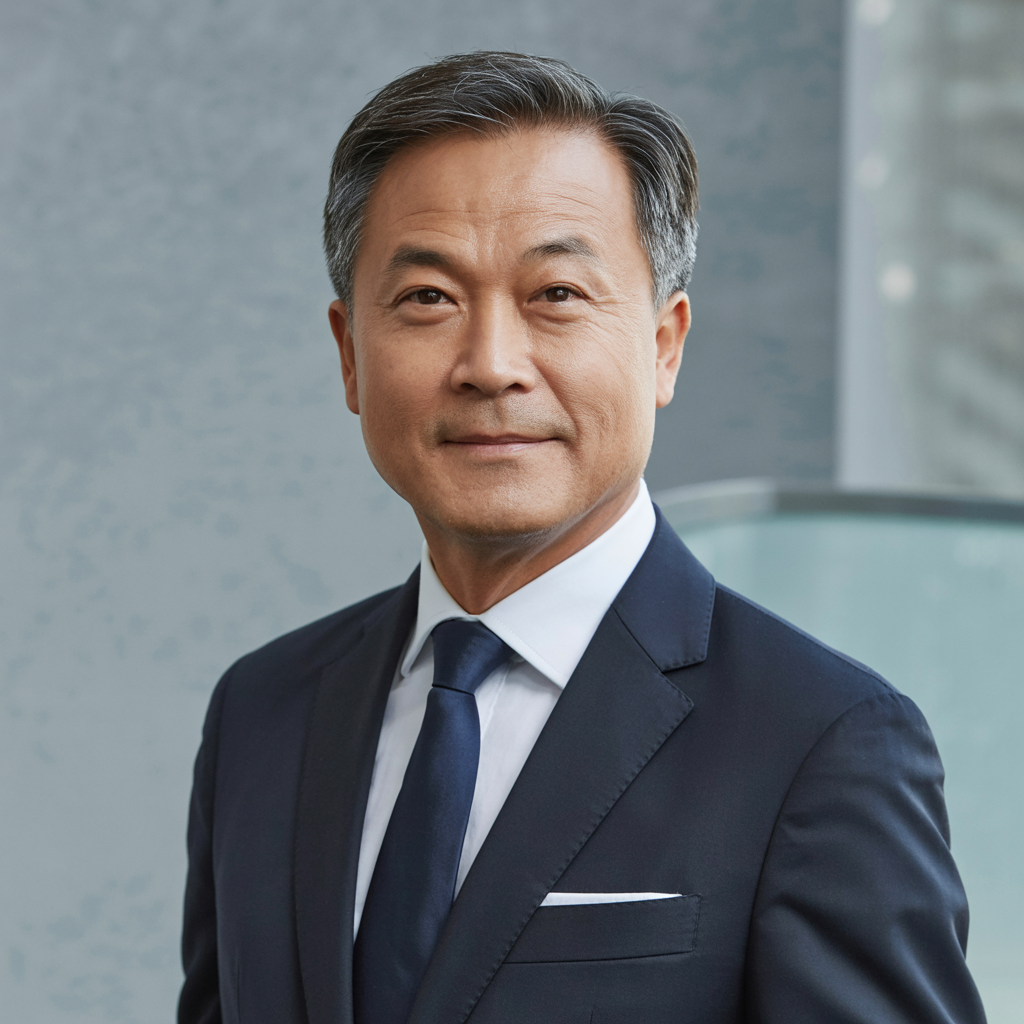
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Get Expert Guidance — Contact Our Team
This information is general and is current for the 2025–26 financial year at the time of publication. ATO thresholds, due dates, concessions and reporting requirements can change. Every business situation is different, so obtain advice for your records and confirm dates shown on your ATO activity statement or registered tax agent lodgement schedule.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files